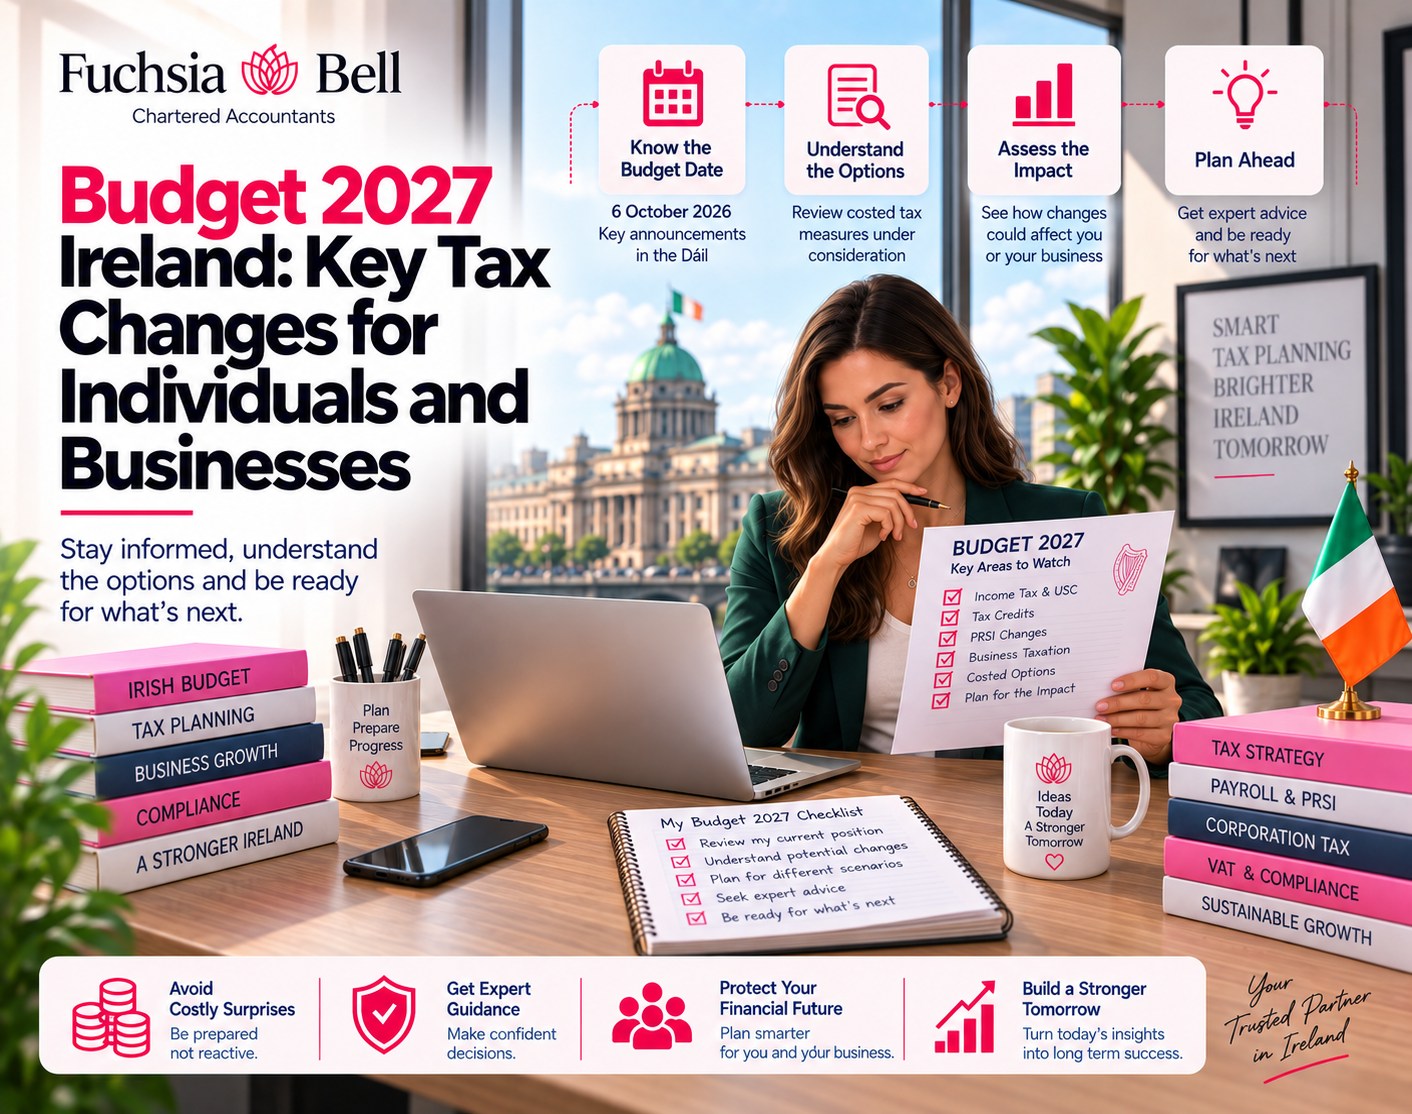
Budget 2027 is delivered on Tuesday 6 October 2026. Nothing on income tax, USC, tax credits, or business taxation has actually been decided yet. What exists right now is a confirmed overall package size, a list of costed options the Department of Finance is considering, and a signalled political theme. Treating any of those as a locked-in change before the Minister for Finance actually stands up in the Dáil is how a lot of pre-Budget coverage ends up wrong.
This is worth being precise about, because one real change is already locked in for October, and it isn’t a Budget measure at all.
What’s Already Confirmed, Separately From the Budget Itself
Employee PRSI rises from 4.2% to 4.35% on 1 October 2026, five days before Budget Day. This was legislated as part of a multi-year PRSI increase schedule agreed previously, not something Budget 2027 itself decides. Employers managing payroll need this change built into October’s pay run regardless of anything announced on Budget Day itself.
The Confirmed Package Size, Before the Detail
The Government’s Summer Economic Statement, published 22 July 2026, confirmed an overall Budget 2027 package of €8.5 billion, split between roughly €7 billion in additional public spending and €1.5 billion in tax measures. That figure sets the outer boundary of what’s affordable. It says nothing about which specific credits, bands, or reliefs the €1.5 billion actually gets spent on, since that detail is exactly what remains undecided until Budget Day. Businesses reviewing their tax services arrangements ahead of October are generally better placed checking their current position than trying to model a package whose detail hasn’t been set.
What’s Actually Under Discussion, Not Decided
The Department of Finance’s Tax Strategy Group met on 9 June 2026 to consider a list of costed options, explicitly not a set of decisions. Widening the standard rate cut-off band beyond its current €44,000 single threshold is one option under consideration, costed at roughly €460 million for every €2,000 of additional width. Increases to the Personal, Employee, and Earned Income tax credits, adjustments to the USC band ceilings, and an extension of the €1,000 Rent Tax Credit are also on the list of possibilities being priced, not measures already agreed. Any confirmed change to credits or bands eventually needs to be reflected in the following year’s income tax return, so tracking what actually gets confirmed matters more than reacting to the options list itself.
Why “Making Work Pay” Is the Signalled Theme
Minister for Finance Simon Harris has described the approach behind Budget 2027 as making work pay, aimed at ensuring a pay rise or promotion doesn’t get eroded by moving into a higher tax bracket. That framing points toward band widening and credit increases over other options, but a signalled political theme and a locked figure in legislation are two very different levels of certainty, and only one of them survives contact with the actual Budget speech unchanged. For a business owner weighing salary versus dividend decisions ahead of the change, this is exactly the kind of question CFO services style planning exists for, modelling more than one outcome rather than betting on a single predicted figure.
When Any Announced Change Actually Reaches Your Pay
Income tax, USC, and tax credit changes announced on Budget Day normally take effect from 1 January of the following year, not from October. A change announced on 6 October 2026 would generally show up in the first payslip of January 2027, not the next pay run after Budget Day. This timing gap is where a lot of confusion happens each year, since Budget Day coverage and the actual pay change land three months apart. On the business side, changes affecting corporation tax or VAT rates sometimes follow a different commencement date entirely, occasionally taking effect from Budget Day itself rather than the new tax year.
What to Actually Do Before 6 October
Planning around specific costed options before they’re confirmed is speculation dressed up as strategy. What’s actually useful before Budget Day is understanding your current position clearly enough to see the effect of whatever does get announced, rather than guessing at numbers that might not survive the final package. For a business, this typically means having current-year VAT return and payroll costs clearly laid out, so a rate or threshold change on Budget Day has an immediate, calculable impact rather than requiring a fresh review from scratch.
Frequently Asked Questions
Will income tax rates themselves change in Budget 2027?
The 20% and 40% rate structure has stayed unchanged across recent budgets, with adjustments typically coming through the band width or credits rather than the headline rates. Nothing is confirmed either way until the Budget is delivered.
Does the PRSI increase to 4.35% apply to employers as well as employees?
Employer PRSI is on a separate multi-year schedule of its own increases, so the October 2026 change should be checked against both employee and employer rates rather than assumed to be identical.
Why does pre-Budget coverage sometimes contradict itself?
Different outlets often report Tax Strategy Group options, political party submissions, and confirmed Government positions as though they carry equal weight, when only the Government’s own confirmed measures on Budget Day actually become law.
Is the Rent Tax Credit guaranteed to continue?
It has been extended in previous budgets, but continuation for 2027 is listed among the options being considered rather than something already confirmed.
When will the actual confirmed figures be available?
On Budget Day itself, 6 October 2026, when the Minister for Finance delivers the speech and the Department of Finance publishes the full set of measures.
Reviewing Your Position Once the Real Numbers Land
The most useful moment to act on Budget 2027 isn’t the weeks before it, spent reacting to costed options that may never be chosen. It’s the days immediately after, once the actual bands, credits, and business measures are confirmed and can be checked against your specific numbers rather than a general estimate. A broader look at how Irish SMEs typically plan around Budget-driven changes to salary, dividends, and business structure is covered on geroconnor.info, and a fuller picture of how online chartered accountants work through Budget season with clients is covered there too.