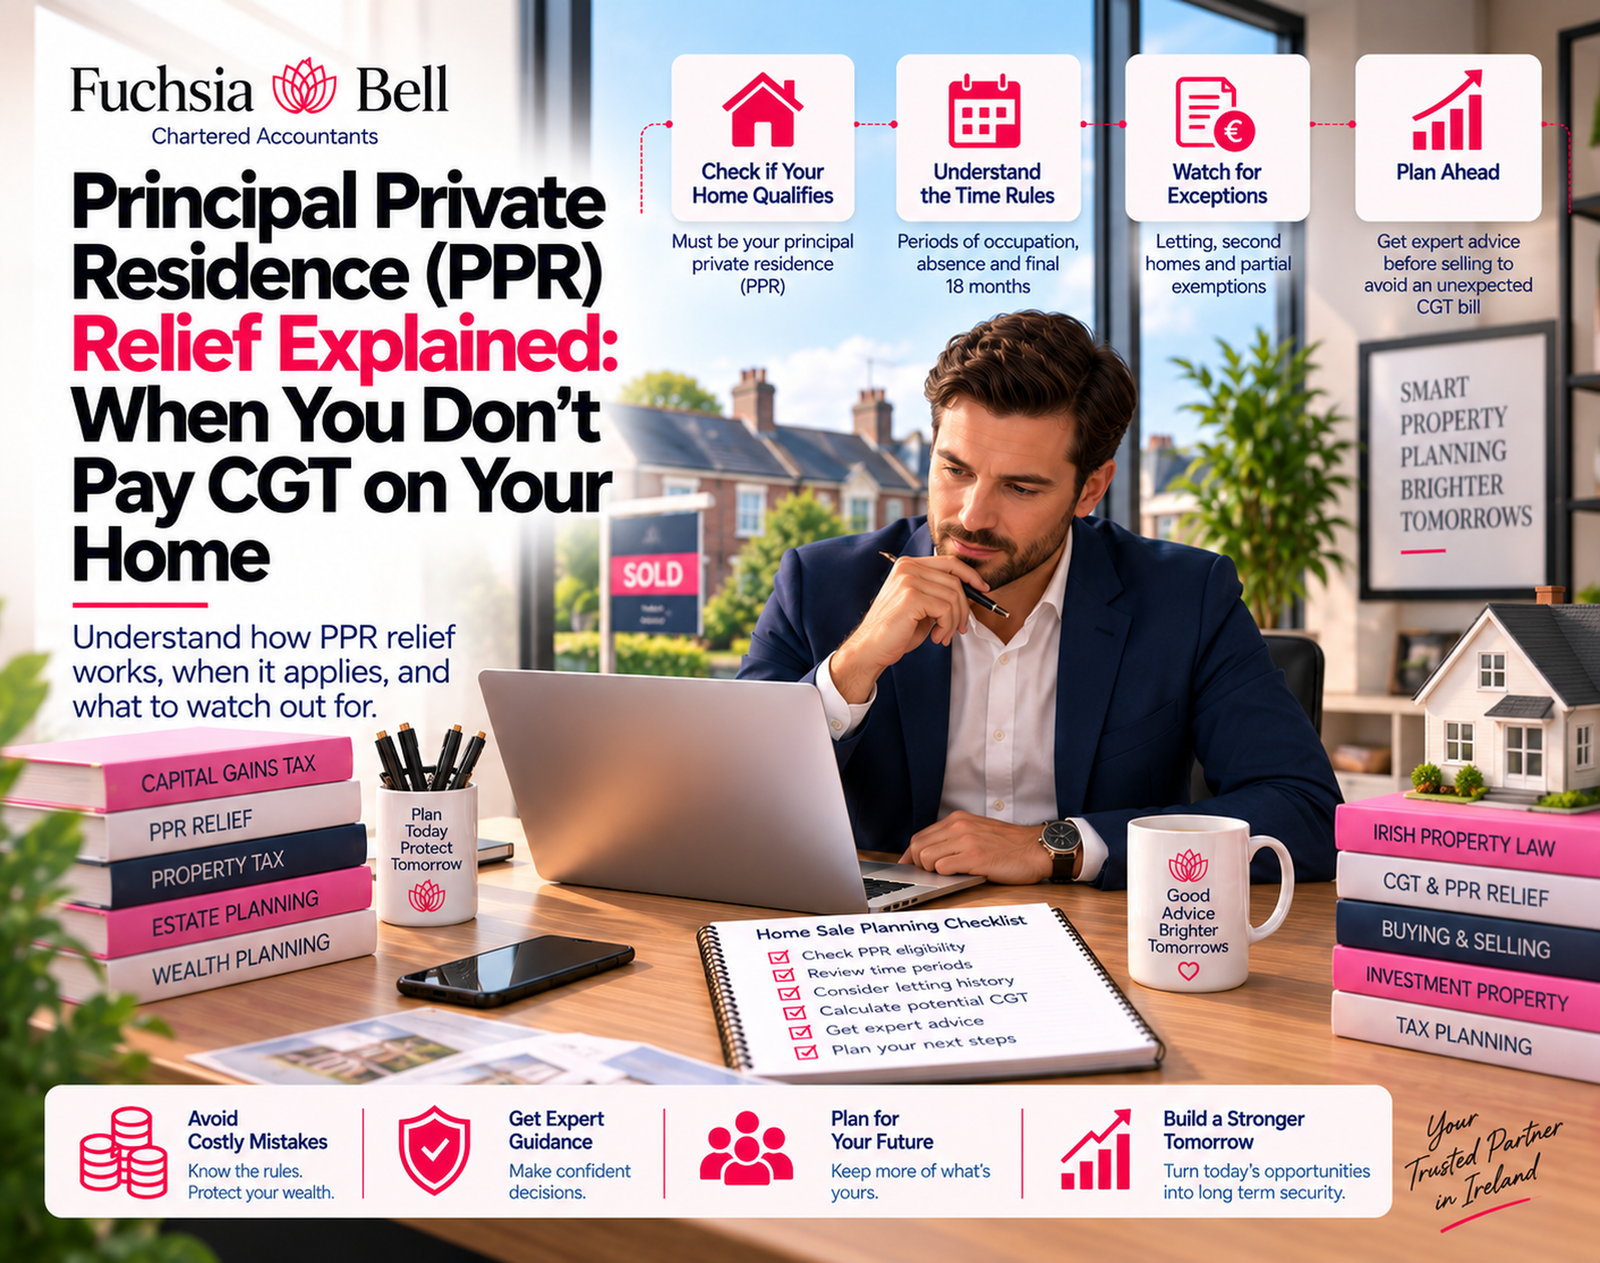
Most people selling a home in Ireland assume the full gain is tax-free. Section 604 of the Taxes Consolidation Act 1997 only exempts the portion of the gain that arose while the property was genuinely your main residence. If the history is clean, the full gain is covered. If it is not, parts of it are chargeable at 33% and the amount due can come as a real shock.
How Revenue Works Out the Exempt Portion
The calculation is a fraction: qualifying period divided by total ownership period, multiplied by the total gain. Qualifying period covers the time you actually lived there, any Revenue-approved absence periods, and the final 12 months of ownership regardless of whether you were still there at the end. If the property was your home from purchase to sale, the full gain is exempt and nothing further needs to be worked out.
The Final 12 Months Rule
The last 12 months of ownership always count as deemed occupation, even if you had already moved out before the sale completed. Most sellers move into their next property before the old one exchanges, and without this provision every month the house sat empty would reduce the exempt fraction. Before December 2019 Revenue allowed 18 months here. It was cut to 12, and that shorter window matters most for properties that spent a long time on the market.
Does Letting the Property Affect the Relief?
Renting a room under the rent-a-room scheme while living there yourself does not affect the relief at all. Letting the full property for a period of years is different. Those years sit outside the qualifying period and the gain for that time is chargeable at 33%, minus whatever the final 12-month rule absorbs. Letting a self-contained part of the property exclusively as a separate rental unit restricts the relief by the proportion of the building that was never your personal living space.
| Arrangement | What Revenue Does With It |
| Rent-a-room while living there | No impact on relief |
| Full property let for a period | Chargeable for those years, minus final 12 months |
| Part of property exclusively let | Relief cut by that proportion |
| Short-term holiday letting of full property | Only non-let periods qualify |
What Absence Periods Does Revenue Accept?
Section 604(5) protects three categories as deemed occupation: working abroad in any employment (no time limit), working elsewhere in Ireland for employment reasons (up to 4 years), and any other absence (up to 4 years total). Each requires the property to be your PPR before and after the absence and must not have been let during it. Clean bookkeeping of letting dates and occupation periods is what makes any of these periods verifiable with Revenue years later when the property eventually sells.
What If You Owned Two Properties at Once?
Revenue only recognises one principal private residence per person at any given time. If you owned two properties and used both, you had two years from acquiring the second to elect which was your PPR in writing to Revenue. Miss that window and Revenue makes the call based on where you are registered, where the family lives, and where utility accounts run. Once the property has sold without a valid election on file, the options to manage the CGT position are very limited.
Does Business Use of Part of the Home Affect the Relief?
If part of the property was used exclusively for business and never for personal use, the relief is restricted by that proportion. A dedicated office never used personally creates a small chargeable element on sale. The key word Revenue focuses on is exclusively. Rooms used for both personal and business purposes do not trigger the restriction. A fully ring-fenced business space does.
What Does the Calculation Actually Look Like?
Bought January 2013, sold January 2026. Lived there until January 2020 (7 years), let fully from 2020 to 2026 (6 years). Total ownership: 13 years. Qualifying period: 8 years. Exempt fraction: 61.5%. On a gain of €280,000, the chargeable portion is €107,800. The standard capital gains tax rate of 33% gives approximately €35,574 before the annual CGT exemption of €1,270. Six years of letting history created a €35,000 liability on a property the owner assumed was fully covered.
Frequently Asked Questions
Does PPR relief apply to an inherited property?
Yes. The qualifying period runs from the date of inheritance. The cost base for CGT is the market value at that date, not what the original owner paid.
Can a married couple each claim PPR on separate properties?
No. Spouses are treated as one unit. One PPR between them at any given time, not one each.
Does a home office reduce the relief?
Only if used exclusively for business and never for any personal purpose. Dual-use rooms create no restriction.
Is there a minimum period you need to have lived there?
No statutory minimum. A short genuine period of occupation creates some qualifying period. Properties bought specifically to make a gain on disposal are excluded under Section 604(14).
Working With Us Before the Sale Completes
A restricted PPR claim is manageable before contracts are signed and very hard to fix after the sale completes. At Fuchsia Bell we map the full ownership history before a property sale proceeds, identify where the chargeable element sits, and make sure the income tax return reflects the correct position. We work with clients across Kerry and nationally, including cases involving letting history, extended absences, and two-property situations.
Who We Work With
A conversation before the sale costs far less than a Revenue query after it. For anyone navigating a disposal with a complex ownership history, the CGT guides on GEroConnor’s site cover the wider picture, and their tax services page outlines how the two practices work together on disposals where both personal and business assets are involved.